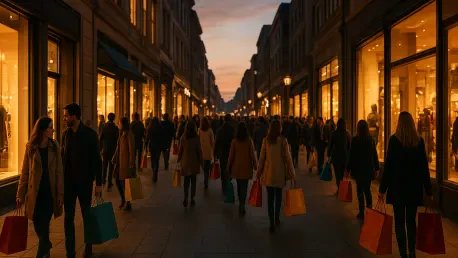
The persistent ability of American households to maintain robust retail activity while facing a twenty percent surge in fuel costs and soaring wholesale inflation is challenging the fundamental laws of economic gravity as 2026 progresses toward its final quarter. Despite a significant spike in wholesale costs, the American consumer continues to spend at record levels, defying traditional economic gravity. As of late 2026, the US economy faces a critical juncture where “gritted teeth” resilience meets the hard reality of 6.3% wholesale inflation and rising interest rates. This article analyzes current spending data, the psychological drivers of consumer behavior, the impact of energy-driven inflation, and expert outlooks on the sustainability of this economic trend.
Assessing the DatThe Paradox of Growth and Inflation
Current Indicators and Economic Momentum
The most striking feature of the current economic landscape is the sharp acceleration in wholesale price pressures. According to the government producer price index, wholesale costs rose by 6.3% in September 2026 compared to the previous year, marking the most aggressive spike in nearly four years. This upward momentum was further evidenced by a 1.3% monthly jump, a movement almost entirely powered by a 20% surge in gasoline prices. Such figures suggest that the inflationary cooling observed in prior months has been replaced by a renewed heat that threatens to ignite consumer prices across the board.
In contrast to what standard economic theory would suggest, retail sales performance has remained unexpectedly robust. September recorded a 0.8% increase in retail sales, significantly outperforming most analyst forecasts. While a substantial portion of this gain was technically driven by higher prices at the pump, which accounted for a 6.4% jump in gasoline station receipts, the underlying demand across other categories remained firm. This suggests that the momentum of the American economy is being carried by a consumer base that refuses to blink, even as the cost of basic goods continues to climb.
The energy factor remains the primary engine of this inflationary pressure, creating a significant “bleed-through” effect across the domestic supply chain. With gasoline prices surging, the secondary impacts on shipping, warehousing, and food production costs are becoming impossible to ignore. Wholesale food prices saw a 1.2% rise in a single month, signaling that the relief consumers hoped for in grocery aisles is likely to remain elusive. This cascading effect ensures that every sector, from manufacturing to retail, is grappling with an elevated cost structure that eventually filters down to the end user.
Real-World Manifestations of Consumer Resilience
Daily spending habits provide the clearest evidence of how Americans are navigating this high-cost environment. Discretionary spending trends, specifically a 1.1% increase in spending at restaurants and bars, indicate that many households are still prioritizing lifestyle maintenance. This willingness to spend on experiences and dining out, despite the erosion of purchasing power, suggests that the collective psychological desire for normalcy continues to outweigh the cautionary signals of the broader market.
However, the logistical backbone of the country is feeling the strain of the diesel dependency. With diesel prices averaging $6.32 per gallon, the long-haul trucking and freight sectors are being forced into difficult logistical adjustments. Since the majority of domestic freight is moved by diesel-powered vehicles or trains, these elevated fuel costs are directly translating into higher retail prices for finished goods. This pressure is particularly acute for smaller transport firms that lack the capital to absorb such significant increases in operating expenses over the long term.
To maintain this level of spending, household financial shifts are becoming increasingly apparent across the country. There is an observed and growing reliance on credit cards and personal savings to bridge the widening gap between stagnant wages and rising retail prices. As financial cushions built up in previous years begin to erode, the sustainability of this “spending at all costs” mentality is being called into question. Households are effectively betting on continued job security to justify their current debt loads, creating a precarious balance in the domestic economy.
Perspectives from Economic Thought Leaders
The Psychology of Job Security
The primary anchor for continued consumer confidence is the remarkable stability of the labor market. Historically low layoff rates, which have remained consistently below 200,000 weekly unemployment claims, create a powerful psychological safety net for the average worker. When people feel that their income is secure, they are much more likely to continue spending, even if the cost of living is rising. This sense of invulnerability is currently the strongest defense against a potential economic slowdown.
The Monetary Policy Debate
This confidence is being tested by an intensifying monetary policy debate within the halls of power. Federal Reserve Chairman Kevin Warsh has moved to implement rate hikes to combat the persistent 3.7% inflation rate, while simultaneously facing political pressure for renewed stimulus. The tension between the need to cool the economy and the desire to maintain growth has created a volatile environment for investors. The recent quarter-point hike to approximately 3.9% marks a definitive shift toward a more restrictive monetary stance aimed at taming the price surges seen in the producer price index.
The Wage-Price Gap
Expert analysis of the current landscape highlights a concerning development: the first decline in inflation-adjusted weekly paychecks since May. This wage-price gap represents a fundamental threat to long-term purchasing power, as it indicates that even those with stable jobs are effectively seeing their standard of living decrease. While consumers can use credit or savings to maintain their lifestyle temporarily, the widening chasm between what people earn and what things cost cannot persist indefinitely without a significant correction in spending habits.
The Future Outlook: Stability or Contraction?
Monetary Tightening Impact
The implications of the Fed’s 3.9% interest rate are only beginning to ripple through the broader economy. With further hikes likely before the end of the year, the cost of mortgages, car loans, and consumer debt will continue to rise. This monetary tightening is designed to reduce the money supply and slow inflation, but it also increases the financial burden on households that are already struggling with high energy costs. The cumulative effect of these higher interest rates could eventually serve as the breaking point for consumer resilience.
The Labor Market Friction
Friction is also appearing in the labor market, where job creation has slowed to a crawl. September figures showed only 29,000 new positions added to the economy, a sharp drop from the growth seen earlier in the year. While the unemployment rate remains relatively low at 4.2%, the stagnation in hiring suggests that businesses are becoming more cautious in the face of rising wholesale costs and interest rates. If job growth continues to stall, the psychological safety net that has supported consumer spending will likely begin to unravel.
Sustainability of the Muscling Through Phase
Determining how much longer consumer confidence can serve as the primary engine for economic growth is the central question for late 2026. The “muscling through” phase has been impressive, but it is increasingly reliant on debt rather than real wage growth. As financial cushions disappear and the cost of borrowing becomes more expensive, the economy faces a potential transition from resilience to exhaustion. The transition period between these two states will be critical for determining the trajectory of the national economy over the next several quarters.
Potential Trajectories
Economists are currently weighing two primary trajectories for the near future: a high-altitude stabilization or a sharp decline in discretionary spending. Stabilization would require a cooling of energy prices and a moderation of inflation that allows wages to catch up. Conversely, if energy costs remain high and the labor market continues to weaken, a significant contraction becomes more probable. The path taken will depend largely on whether the consumer can withstand the dual pressures of expensive energy and rising interest rates without a significant increase in unemployment.
Summary and Conclusion
The economic climate of late 2026 demonstrated a remarkable but fragile equilibrium where high employment confidence collided with the eroding power of the American paycheck. While the consumer remained the backbone of the national economy, the analysis showed that the margin for error narrowed significantly as energy costs and credit prices increased. The data revealed that the reliance on savings and debt to maintain lifestyle standards created a vulnerability that could not be ignored by businesses or policymakers.
Strategic adjustments were required as the focus shifted from simple spending resilience toward the risk of widespread financial exhaustion. It became clear that monitoring the relationship between real wages and energy-driven inflation was the most critical factor for predicting the next phase of the economic cycle. Stakeholders recognized that for the economy to maintain its current momentum, a stabilization of wholesale costs was necessary to prevent a more profound shift in consumer behavior. The period served as a reminder that psychological confidence, while powerful, must eventually be supported by sustainable financial foundations to avoid a broader contraction.