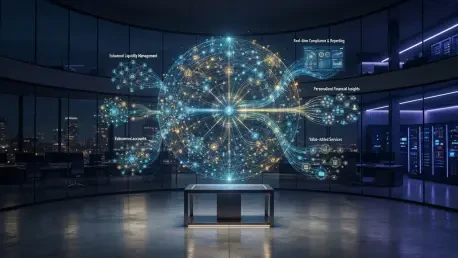
Banks that continue to rely on manual back-office processes for payment investigations are missing the efficiency gains offered by structured reason codes and time-stamped flows. As the global migration toward the ISO 20022 standard nears its final stages, the financial industry finds itself at a critical crossroads where technical compliance must evolve into commercial strategy. For many institutions, the heavy lifting of updating infrastructure is largely finished, yet the expected return on investment remains elusive because data is still being treated as a secondary byproduct rather than a primary asset. When a bank receives a rich ISO 20022 message only to convert it back into a legacy format for internal processing, it effectively strips away the very intelligence that makes the new standard valuable. This loss of enrichment impacts everything from sanctions screening to fraud detection, creating a self-imposed ceiling on operational performance and client service innovation that will define the winners of the next decade.
1. Identifying Three Primary Categories of Value
The initial pool of value centers on the internal efficiency of the bank, where the impact of structured data is most immediate and measurable. By utilizing granular party information and purpose codes, institutions can significantly sharpen their sanctions screening processes, reducing the volume of false positives that currently plague compliance departments. Furthermore, structured reason codes allow for the automation of exception handling, which historically required human intervention to decipher ambiguous free-text fields. This operational shift does more than just lower costs; it improves the bank’s overall risk profile by ensuring that every transaction is categorized with a level of precision that was impossible under older protocols. Beyond compliance, time-stamped payment flows enable treasurers to refine their intraday cash forecasting. This precision allows banks to reduce idle liquidity buffers, effectively freeing up capital that can be deployed into more productive, interest-bearing assets across the global market.
Building on internal gains, the second category of value focuses on turning enriched data into premium services for corporate clients. Modern treasurers are increasingly demanding the same level of transparency and speed in business payments that they experience in their personal lives. By providing structured remittance fields—which carry invoice numbers, purchase orders, and credit note references—banks can facilitate end-to-end automated reconciliation through treasury APIs. This eliminates the need for manual back-office intervention at the client level, creating a sticky and high-margin relationship between the bank and the corporate entity. Furthermore, the consistency offered by ISO 20022 across different real-time gross settlement systems allows for a consolidated view of cash positions across multiple geographies. This visibility is vital for liquidity management in a volatile economic climate, turning the bank from a simple utility provider into a strategic partner that offers the data-driven insights necessary for complex financial decision-making.
2. Transitioning From Regulatory Compliance to Revenue
The journey toward monetization begins with a rigorous six-month focus on strengthening the underlying data infrastructure. Banks must move decisively toward native ISO 20022 processing, effectively retiring the internal translation engines that often act as a bottleneck for data richness. This phase requires a comprehensive data-quality initiative that goes beyond mere transmission to focus on the remediation of legacy records, such as unstructured postal addresses, before upcoming industry deadlines. By establishing a cross-functional team that includes representatives from risk, compliance, product development, and data science, banks can ensure that payment data is governed as a strategic asset rather than a technical requirement. This period is also the ideal time to build an inventory of current data holdings and assess their completeness regarding Legal Entity Identifiers and purpose codes. While this foundational work does not generate immediate revenue, it creates the essential platform upon which all subsequent commercial offerings are built.
As the foundation solidifies, the focus shifts toward the actual delivery of value-added services and the pilot testing of new commercial models over a period of seven to eighteen months. During this window, banks should begin integrating structured data into their anti-money laundering and fraud detection systems to realize the benefits of reduced false positives and more accurate threat assessments. On the client-facing side, the introduction of automated reconciliation tools for specific corporate segments can serve as a proof of concept for broader market launches. Analytics dashboards that provide purpose-code insights or correspondent banking performance metrics can be offered as premium features, allowing clients to optimize their own internal workflows. Critically, this phase is when the bank must finalize its privacy and data-governance frameworks to support future external products. By ensuring that all data usage aligns with evolving open-finance regulations, the institution protects its reputation while preparing to participate in the broader data economy.
3. Frequently Asked Questions
One of the most common inquiries involves why native ISO 20022 processing is fundamentally superior to traditional message translation. When a bank relies on translating a rich message back into an older format like MT, it often loses the specific details—such as structured addresses or detailed remittance information—that the standard was designed to carry. This loss prevents downstream systems, like those used for reconciliation and sanctions screening, from utilizing the data effectively, essentially negating the benefits of the upgrade. Another critical question concerns the consequences of treating the migration purely as a compliance exercise. Institutions that take this narrow view will likely incur the significant costs of updating their systems without ever capturing the revenue-generating potential of the data they are now required to handle. These banks risk falling behind competitors who use the enhanced data to offer more sophisticated treasury services, faster settlement times, and more accurate fraud prevention, ultimately leading to a loss of market share.
Regarding security, industry experts often ask how ISO 20022 improves fraud prevention capabilities. The standard provides structured fields that give much-needed context to every transaction, allowing for more precise behavioral modeling and the detection of anomalies like authorized push payment scams. Looking back at the successful strategies deployed, it is clear that banks which prioritized data integrity and cross-departmental collaboration achieved the highest returns. They moved beyond simple technical adherence and instead positioned themselves as data partners in a new open-finance landscape. The most successful institutions were those that recognized early on that the value of the message was not just in the movement of funds, but in the intelligence carried within the instruction itself. By treating data as a strategic product, they created new revenue streams from market intelligence and premium treasury services. Ultimately, the transition was defined by those who viewed the new standard as a platform for growth rather than a regulatory burden to be managed.