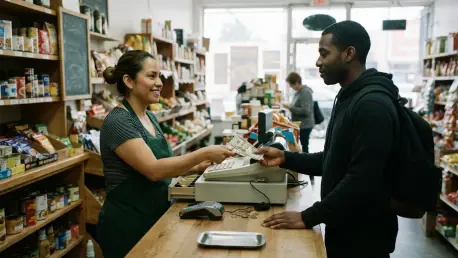
Proponents of the ban, including Councilmembers Eunisses Hernandez and Hugo Soto Martínez, contend that a truly inclusive city cannot permit the systemic exclusion of those without bank accounts. While digital payment technologies have streamlined the shopping experience for millions, they have also inadvertently created a tiered society where those lacking credit or debit access find themselves effectively barred from basic commerce. In a sprawling metropolis like Los Angeles, where the digital divide remains a stark reality for diverse communities, the push to maintain physical currency is seen as a vital protection for the unbanked population. Despite years of intense debate and multiple legislative attempts to mandate cash acceptance, the city council has found itself caught in a web of bureaucratic delays and competing interests. As of late 2026, the absence of a formal ordinance means that the local marketplace continues to evolve without a unified standard for payment accessibility.
Legislative Progress: The Path of Policy Delays
Part 1: A Legislative Timeline
The legislative journey toward a cash mandate in Los Angeles began as a response to the growing number of businesses adopting card-only policies, which critics argued was a form of economic discrimination. Councilwoman Heather Hutt initially spearheaded this movement, introducing a formal motion designed to compel retailers to accept physical bills and coins. This initiative gained significant traction as social justice advocates highlighted the plight of low-income residents who rely exclusively on cash for their daily needs. Throughout the early stages of the proposal, there was a palpable sense of urgency within the council chambers to establish a policy that mirrored the protections already in place in other major California cities. However, the initial momentum soon gave way to a series of extensive reviews and requests for legal analysis. These procedural steps were intended to ensure that any new law would be robust enough to withstand challenges while addressing the business landscape.
By the beginning of 2026, the discourse surrounding the cash mandate shifted toward a more cautious approach as council members weighed the potential economic repercussions. A pivotal vote took place in January 2026, where the City Council decided unanimously to defer immediate action in favor of conducting additional research into the needs of various business sectors. This decision effectively placed the ordinance on a long-term hold, extending the period of uncertainty for both consumers and business owners. While the council expressed a continued commitment to financial equity, the delay reflected pressure from industry groups who argued for more operational flexibility. Consequently, the progress toward a mandatory cash policy has been stalled for months, leaving the city in a state of limbo. This period of study was intended to bridge the gap between different viewpoints, yet it has also highlighted the difficulty of reconciling digital innovation with fundamental financial access.
Part 2: Identifying the Regulatory Strategy
The socioeconomic implications of the cashless trend are particularly profound for Los Angeles, a city defined by its immense diversity and large immigrant populations. Research has consistently shown that a significant percentage of Latino and Black households remain unbanked or underbanked, making them uniquely vulnerable to digital-only payment models. For these individuals, cash is not simply a matter of convenience; it is the only reliable way to purchase essential goods such as groceries and medicine. When a local retailer decides to stop accepting physical currency, it sends a clear signal to these community members that their business is no longer welcome. This dynamic risks creating commercial deserts where specific demographics are unable to access vital services within their neighborhoods. Advocates for the ban argue that such exclusion is a regression in civil rights, as it creates an invisible barrier to participation in the local economy for those who have been marginalized.
Furthermore, the push for a cash-friendly city is about preserving the autonomy of seniors and youth who may not have access to sophisticated mobile banking or credit facilities. Many older residents have spent decades operating in a cash-based economy and find the transition to digital-only platforms to be both confusing and intimidating. Similarly, young people who have not yet reached the age of financial independence rely on physical money for small purchases and learning fiscal responsibility. A citywide mandate would ensure that these groups can navigate the marketplace with confidence and independence, regardless of their technological literacy. Beyond financial inclusion, proponents believe that cash serves as a critical safety net during times of digital infrastructure failure or natural disasters. By ensuring that cash remains valid, Los Angeles would be fortifying its economic resilience and ensuring that no resident is left behind during the transition toward a digital future.
Socioeconomic Impacts: Equity and Operations
Part 3: Financial Rights of the Unbanked
From the perspective of many business owners, the transition to a cashless operation is primarily a strategy aimed at enhancing safety and operational security. Physical currency has long been a magnet for criminal activity, making retail establishments with high cash volumes prime targets for robberies. By eliminating cash transactions, businesses can significantly reduce the amount of money held on-site, thereby lowering the risk of violence against employees and minimizing financial losses from theft. This shift has been particularly popular among small business owners who may not have the resources to invest in high-end security systems or armed guards. For many, the ability to operate in a card-only environment provides a sense of peace of mind that outweighs the potential loss of customers who prefer to pay with bills. Industry representatives have argued that forcing these businesses to return to a cash-based system would unfairly expose them to greater risks and undermine staff safety.
In addition to security benefits, the management of cash involves a wide range of logistical challenges and administrative costs that can strain the resources of a modern enterprise. Processing physical money requires employees to spend significant time counting drawers and preparing bank deposits, all of which represent labor hours that could be redirected toward customer service. There are also direct costs associated with cash handling, such as purchasing safes and paying for armored car transport to manage deposits safely. Digital transactions, by contrast, offer a streamlined and automated paper trail that simplifies accounting and reduces the administrative burden on management. Opponents of the mandate believe that the government should not dictate operational choices that impact a company’s bottom line and efficiency. They contend that in a competitive market, businesses should have the autonomy to choose the payment methods that best suit their unique business models and customers.
Part 4: Future Outlook and Solutions
The legislative frameworks proposed in Los Angeles have attempted to find a middle ground by introducing specific limitations and exemptions for certain types of retail environments. Early drafts of the ordinance suggested that businesses should be required to accept cash only for transactions up to a certain threshold, such as $1,000, while allowing them to refuse large-denomination bills like $100s. This approach was designed to mitigate security risks while ensuring that the vast majority of consumers could make standard purchases. Additionally, exemptions were considered for businesses where cash handling is impractical, such as online marketplaces, parking garages, and large-scale entertainment venues that utilize mobile-only systems. These carve-outs were intended to provide businesses with the flexibility they need to operate modern facilities while still upholding the core principle of accessibility. By refining these guidelines, policymakers hoped to create a balanced law for everyone.
While the debates in Los Angeles continued through 2026, the city remained a notable outlier compared to other jurisdictions that implemented cash-protection laws. To resolve the stalemate, the municipal government sought to establish a dedicated task force focused on developing pilot programs that incentivized businesses to maintain cash options without compromising security. These initiatives aimed to provide technological subsidies for secure cash-handling equipment, bridging the gap between digital convenience and physical accessibility. The council also explored the possibility of creating more robust municipal banking options that helped unbanked residents transition into the digital economy over time. By shifting the focus from a strict mandate to a collaborative strategy, the city moved toward a model that prioritized financial inclusion while respecting the operational realities of commerce. This proactive approach suggested that the future of payment systems in Los Angeles would be defined by accessibility for all.