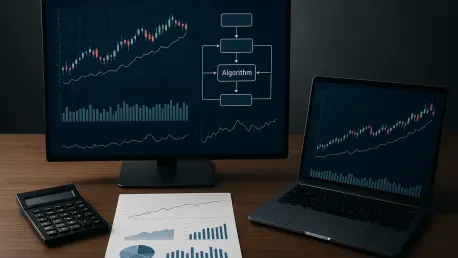
A model might identify a specific asset pattern, but the final holding depends on whether that asset fits within the portfolio’s exposure limits. This fundamental distinction separates the act of finding investment opportunities from the discipline of managing a cohesive investment portfolio. In 2026, algorithmic systems have evolved to handle vast streams of alternative data, yet the core principles of diversification and risk management remain the primary drivers of long-term success. Unlike high-frequency trading, which focuses on rapid execution for small price discrepancies, algorithmic portfolio management seeks to maintain a target risk-reward profile through systematic rebalancing and asset allocation. These systems operate within a set of predefined constraints, ensuring that the resulting investment mix aligns with the specific financial goals, time horizons, and risk tolerance of the individual or institutional investor. By removing emotional bias from the allocation process, these mathematical frameworks provide a consistent methodology for navigating volatile markets. However, the efficacy of such an approach is entirely dependent on the quality of the underlying model, the integrity of the data inputs, and the robustness of the governance structures that oversee the algorithm’s behavior. Understanding how these components interact is essential for any professional looking to assess the reliability of a modern systematic investment strategy. The transition from raw data to a balanced portfolio involves several critical stages, each requiring precise calibration to ensure that the final output matches the investor’s original mandate without introducing unintended systemic risks.
1. Understanding the Methodology: Moving from Data to Action
A systematic approach does not jump straight from a market observation to a trade; instead, it follows a structured sequence to ensure every decision is grounded in the investor’s original strategy. The first critical step involves establishing clear goals, which means defining the investment purpose, the intended time frame, and the specific risk comfort levels of the client. This foundational phase ensures that the algorithm is programmed to prioritize the right outcomes, such as capital preservation, aggressive growth, or steady income generation. Without these parameters, an algorithm might optimize for short-term gains that conflict with a long-term retirement objective or take on excessive leverage that violates the investor’s risk appetite. By translating qualitative human goals into quantitative constraints, the management system creates a boundary within which the mathematical model must operate. This alignment is what distinguishes a professional portfolio management system from a simple speculative tool. It allows the system to ignore market noise that does not serve the specific objective while remaining focused on the metrics that matter most to the portfolio’s ultimate success in the current 2026 economic landscape.
Once the objectives are set, the system moves to the data organization phase, where it gathers and cleans relevant information to fix any inconsistencies or gaps that might skew the results. This stage is often the most labor-intensive part of the process, as it involves aggregating data from dozens of sources, including traditional financial statements, real-time market pricing, and alternative data like satellite imagery or consumer sentiment indices. The algorithm must verify the timestamps of this data to ensure that no “look-ahead” information is being used, which would lead to unrealistic simulations. Cleaning the data involves removing outliers that represent glitches rather than market movements and normalizing different data types so they can be compared accurately. This rigorous preparation ensures that the subsequent calculations are based on a reliable foundation. In 2026, the proliferation of data sources has made this step even more vital, as the volume of information can easily overwhelm a system that lacks robust filtering mechanisms. A well-organized dataset allows the model to identify genuine trends and correlations that might be invisible to a human analyst, providing a competitive edge in identifying emerging market shifts before they are fully priced in.
Following the data preparation, the algorithm proceeds to calculate projections, using the organized information to project potential risks, returns, and how different assets move together. These are not certainties but are sophisticated estimates based on historical behavior and current market indicators. The system analyzes the covariance between assets to understand how a decline in one sector might be offset by a gain in another, which is the mathematical basis for effective diversification. In 2026, these projections have become increasingly complex, incorporating non-linear relationships that traditional models often missed. For example, the system might project how a change in central bank policy affects not just interest rates but also consumer discretionary spending and emerging market currency stability. These projections provide the raw material for the portfolio construction phase, where the model determines the optimal weights for each holding. It is important for investors to recognize that these outputs are entirely dependent on the assumptions built into the model. If the assumptions about market volatility or asset correlations are flawed, the resulting projections will lead to suboptimal portfolio choices, highlighting the need for continuous model validation and empirical testing.
The final phases of the methodology involve building the portfolio and executing the necessary decisions. Building the portfolio involves using a specific method, such as mean-variance optimization or a Black-Litterman approach, to turn projections into actual asset weights while staying within the defined rules. This process considers transaction costs and liquidity constraints, ensuring that the proposed changes are actually feasible in the live market. Once the target weights are finalized, the system converts these plans into specific trading orders. This execution stage must be handled with care to minimize market impact, especially for large portfolios where sudden orders could move prices unfavorably. After the trades are implemented, the system enters a cycle of tracking and adjustment. It continually observes the portfolio’s behavior against its benchmark and stated goals. If market conditions shift outside of the model’s original logic or if the portfolio’s asset allocation drifts too far from the target due to price movements, the strategy must be re-evaluated and rebalanced. This closed-loop system ensures that the portfolio remains dynamic and responsive to new information, maintaining its alignment with the investor’s objectives even as the financial environment evolves through 2026 and beyond.
2. Comparing Management Strategies: Logic and Adaptability
Different algorithmic methods use different logic to reach a decision, and investors must compare them based on how easy they are to understand and how they react to new information. A rules-based system is perhaps the most straightforward approach, utilizing clear “if/then” logic to manage assets. For instance, a rule might state that if a stock’s price falls 10% below its 50-day moving average, the system should automatically reduce the position size by half. This methodology is highly transparent and easy to audit, as every action can be traced back to a specific, human-defined rule. It excels in environments where market behavior is relatively stable and historical patterns are expected to repeat. However, the primary drawback of rules-based systems is their rigidity; they only change when the rules are manually updated by a human manager. In a rapidly shifting market, such as those seen in the first half of 2026, a static rule might become obsolete or even counterproductive. Despite this, many institutional investors prefer rules-based logic for its predictability and the ease with which it can be integrated into broader compliance and regulatory frameworks, providing a clear “paper trail” for every portfolio adjustment.
In contrast to the fixed logic of rules-based systems, optimization-led strategies use advanced mathematical formulas to balance risk and return dynamically. This approach often relies on Modern Portfolio Theory or its modern descendants to identify the “efficient frontier”—the set of portfolios that offer the highest expected return for a given level of risk. An optimization-led algorithm is highly reactive to new data, as even small changes in asset correlations or expected volatility can trigger a recalculation of the entire portfolio’s weights. This sensitivity allows the system to fine-tune allocations with a high degree of precision, seeking to maximize the Sharpe ratio or minimize the maximum drawdown. However, this high level of sensitivity can also be a double-edged sword. If the initial estimates for return or risk are slightly off, the optimizer may recommend extreme or “corner” solutions that are impractical to implement or involve excessive turnover. To mitigate this, managers often apply “shrinkage” techniques or additional constraints to prevent the model from overreacting to noisy data. In 2026, the use of robust optimization techniques has become standard, allowing these systems to handle the inherent uncertainty of market forecasts while still providing a disciplined framework for asset allocation.
The most advanced and increasingly popular approach in 2026 is machine-learning-informed portfolio management. These systems identify complex, non-linear patterns in large datasets that would be impossible for traditional models to capture. By using techniques such as random forests, gradient boosting, or deep neural networks, these algorithms can “learn” from historical data and adapt to new trends as they emerge. For example, a machine-learning model might discover that a specific combination of satellite data, social media sentiment, and supply chain logistics is a leading indicator for the performance of the semiconductor industry. While these models can be incredibly powerful and adaptive, they are often criticized for their “black box” nature. The internal logic can be harder for humans to explain, making it difficult to understand exactly why the model is recommending a specific trade. This lack of interpretability can be a significant hurdle for regulators and risk managers who need to ensure that the system is not taking on hidden risks. To address this, the industry has seen a rise in “explainable AI” (XAI) tools that attempt to peel back the layers of these complex models, providing insights into which features are driving the decision-making process.
When choosing between these strategies, investors must weigh the trade-offs between transparency, adaptability, and performance. A rules-based system offers the highest transparency but the lowest adaptability, while machine learning offers the highest adaptability but the lowest transparency. Optimization-led systems sit somewhere in the middle, offering a rigorous mathematical framework that is more flexible than simple rules but more understandable than a deep learning model. Many modern platforms in 2026 actually use a hybrid approach, combining the strengths of each method. For instance, a system might use machine learning to generate signals, an optimization engine to determine the weights, and a rules-based overlay to enforce risk limits and compliance restrictions. This multi-layered architecture allows for a sophisticated investment process that is both innovative and disciplined. By understanding the underlying logic of each approach, investors can better align their technology choices with their specific needs, ensuring that their algorithmic portfolio management system is fit for the purpose of navigating the complexities of the current global financial landscape.
3. Reviewing and Validating the System: Ensuring Reliability
Because a model’s precision can be misleading, a rigorous review process is essential to ensure that the algorithmic system is performing as intended and not merely benefiting from luck or flawed simulations. The first step in this validation process is to verify data quality and confirm the integrity of the information sources. This involves more than just checking for missing values; it requires a deep dive into the methodology used to collect the data and an assurance that the model isn’t using information that wouldn’t have been available at the time of the trade. This phenomenon, known as data leakage or look-ahead bias, is a common pitfall that can make a strategy look significantly more profitable in a backtest than it would be in reality. For example, if a model uses end-of-day prices to “decide” on a trade that should have occurred at the market open, the results are fundamentally invalid. In 2026, sophisticated auditors use specialized software to trace the lineage of every data point, ensuring that the simulation environment perfectly mirrors the information constraints of the live market. This level of scrutiny is necessary to build trust in the algorithm’s outputs and to ensure that the reported performance metrics are a true reflection of the strategy’s potential.
Another vital component of system validation is performing stress testing and out-of-sample evaluation. A model might perform exceptionally well on the data used to build it—a period known as the training set—but fail miserably when faced with new, unseen information. To test for this, managers split their historical data into two parts: a training set and an “out-of-sample” test set. If the model’s performance drops significantly on the test set, it is a clear sign that the algorithm has “overfitted” to the training data, capturing random noise rather than a meaningful signal. Beyond out-of-sample testing, stress testing involves simulating how the portfolio would behave during extreme market events, such as a sudden geopolitical crisis or a flash crash. In 2026, these simulations often include “what-if” scenarios based on current global tensions or potential shifts in monetary policy. By subjecting the algorithm to these harsh conditions, managers can identify hidden vulnerabilities and ensure that the portfolio’s risk management protocols are robust enough to handle the unexpected. This process provides a necessary reality check, moving beyond theoretical performance to understand the actual risks the investor is carrying in their portfolio.
A robust review must also factor in reality by ensuring the results account for taxes, trading fees, and the actual difficulty of buying or selling assets in the market. Many theoretical models ignore these frictions, leading to performance estimates that are impossible to achieve in a live account. For instance, a strategy that requires high turnover might look profitable on paper, but the costs of frequent trading—including commissions and the bid-ask spread—could quickly erode those gains. Furthermore, the model must consider liquidity constraints; it is one thing to “sell” a small position in a major stock, but quite another to liquidate a large holding in a thinly traded asset without moving the price against yourself. In the current 2026 market environment, where liquidity can dry up rapidly in certain sectors, these considerations are more than just footnotes—they are central to the strategy’s viability. Auditors check whether the backtest includes realistic slippage models and whether it respects the capacity limits of the underlying assets. By incorporating these real-world constraints into the validation process, investors can avoid the disappointment of a strategy that works in a spreadsheet but fails in the brokerage account.
Finally, maintaining ongoing oversight is essential for the long-term health of any algorithmic portfolio. A system that was validated six months ago might become less effective as market dynamics change or as its underlying assumptions are challenged by new economic realities. Effective oversight involves setting up a schedule for human experts to review the model’s behavior, data integrity, and performance attribution over time. This includes analyzing whether the returns are coming from the intended factors—such as specific stock picking—or if they are merely the result of a general market upswing. In 2026, professional firms employ dedicated model risk management teams whose sole job is to challenge the assumptions of the investment algorithms and look for signs of “model decay.” They monitor for drifts in the algorithm’s decision-making patterns and investigate any trades that seem inconsistent with the established strategy. This human-in-the-loop approach ensures that the technology remains a tool for disciplined investing rather than an autonomous source of unmanaged risk. By combining mathematical rigor with professional judgment, investors can create a governance framework that protects their interests and ensures the continued reliability of their algorithmic management systems.
4. Avoiding Common Pitfalls: Managing Complexity and Bias
Even the most advanced algorithms face significant risks, and understanding these pitfalls is crucial for maintaining a stable investment strategy in the 2026 financial environment. One of the most pervasive issues is overfitting, where a model is so complex that it mistakes random market “noise” for a predictable pattern. In their quest for high returns, developers might add too many variables or “features” to a model, allowing it to perfectly explain past data. However, because these patterns were accidental and not based on fundamental economic drivers, they are unlikely to repeat in the future. Overfitted models often show spectacular backtested results but collapse immediately when deployed in live markets. To combat this, modern practitioners use techniques like “regularization,” which penalizes excessive complexity, and “cross-validation,” which tests the model across multiple subsets of data. The goal is to find the simplest model that explains the data effectively, as simpler models are generally more robust and better at generalizing to new market conditions. Recognizing that a high degree of correlation in the past does not guarantee causation in the future is a hallmark of a mature and cautious approach to algorithmic management.
Another dangerous trap is look-ahead bias, which occurs when a simulation accidentally uses future information to make a past “decision.” This can happen in subtle ways, such as using a company’s year-end financial report to simulate a trade that would have occurred in the middle of the year, before the report was actually published. It can also occur when data is “re-stated” by a provider; if the algorithm uses the corrected, updated data instead of the original, potentially flawed data available at the time, the simulation is no longer a realistic test of the strategy. In 2026, the complexity of real-time data feeds has made look-ahead bias harder to detect but even more damaging. Developers must be incredibly disciplined in how they structure their historical databases, ensuring that every data point is “point-in-time” and reflects only what was known at that specific moment. Avoiding this bias is fundamental to the integrity of the entire investment process, as even a small amount of future information can make a mediocre strategy look like a world-class performer. Investors should always ask for detailed documentation on how a firm manages its historical data to ensure that their backtests are not inadvertently “cheating” by peeking into the future.
Ultimately, while algorithms can make the investment process more systematic and disciplined, they cannot eliminate market risk, and human oversight remains vital to ensure that the technology continues to serve the investor’s long-term interests. Market conditions are constantly evolving, and a model that performed well during a period of low interest rates might struggle in a high-inflation environment or during a sudden geopolitical shift. This is known as “regime change,” and it is one of the biggest challenges for any data-driven strategy. Because algorithms rely on historical data to make predictions, they can be slow to adapt when the underlying rules of the market change. This is why professional managers in 2026 do not simply “set and forget” their algorithms; they use them as decision-support tools that are subject to constant review and adjustment. Human intuition and experience are still necessary to recognize when the world has changed in a way that the data does not yet reflect. By maintaining a balance between the speed and objectivity of the algorithm and the context and caution of the human manager, investors can navigate the complexities of the modern market with greater confidence and resilience.
5. Developing Advanced Governance: Actionable Steps for Resilience
The exploration of algorithmic portfolio management demonstrated that successful implementation required a balance of technical rigor and strategic foresight. Stakeholders prioritized the establishment of clear governance protocols and the validation of data integrity over the mere pursuit of high-frequency signals. It was concluded that the integration of machine learning served as a powerful augment to human judgment rather than a total replacement. These findings suggested that the most resilient portfolios were those that accounted for tail risks and liquidity constraints through a systematic framework. Professionals adopted a posture of continuous review, ensuring that every algorithmic decision remained grounded in the stated objectives of the investor. By looking back at the methodologies employed throughout 2026, it became clear that the distinction between a signal and a portfolio holding was the primary anchor for risk management. The industry recognized that while models provided the map, the human-defined constraints and objectives provided the destination, ensuring that technology served the client’s interests rather than operating in a vacuum.
To build on these insights, investors should begin by auditing their current algorithmic tools for data transparency and model interpretability. This involves demanding clear documentation from vendors or internal teams regarding the “point-in-time” nature of their data and the specific logic used for rebalancing. Secondly, a schedule for rigorous stress testing should be established, focusing on scenarios that have not yet occurred but are plausible in the current global economic climate. Thirdly, costs must be meticulously tracked; a strategy that appears profitable but ignores the impact of taxes and slippage should be discarded or refined. Finally, it is essential to foster a culture of skepticism where model outputs are questioned and human oversight is empowered to override the system during clear regime shifts. These actionable steps moved the focus from theoretical performance to operational excellence. By implementing these measures, practitioners ensured that their systematic strategies remained robust, transparent, and aligned with the long-term fiduciary responsibilities they held toward their clients, effectively bridging the gap between automated analysis and professional stewardship.