Market stabilization is becoming the new norm in Australia as vendors across diverse regions and price points adjust their financial expectations downward. This shift has resulted in a staggering $1.64 billion being wiped from original asking prices nationwide, signaling a decisive end to the era of speculative overpricing. Data recently compiled highlights that over 15,850 residential properties are currently listed with significant price reductions, illustrating a broad recalibration of the national housing landscape. This correction reflects a growing disconnect between initial seller optimism and the tempered reality of current buyer capacity. As interest rates and cost-of-living pressures influence purchasing power, the volume of these adjustments suggests that the peak of the market has passed. Investors and homeowners alike are now facing a landscape where transparency and competitive pricing are essential for securing a successful transaction across the various states. The magnitude of these cuts indicates a systemic transition rather than a localized fluctuation.
High-End Adjustments: The Impact on Luxury Real Estate
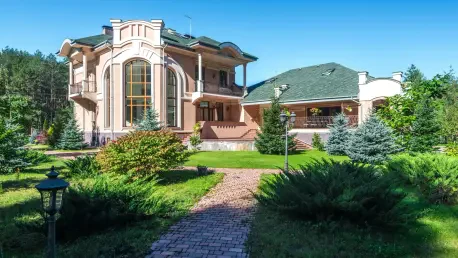
The most dramatic adjustments are appearing at the prestige end of the market, where luxury estates once commanded astronomical figures. For instance, a notable property in Mount Martha on Victoria’s Mornington Peninsula saw its valuation plummet by $5.95 million, shifting from a nearly $15 million asking price down to a more accessible $9 million. Such massive reductions are not isolated incidents but part of a wider trend where high-end sellers are forced to meet the market to attract a shrinking pool of qualified buyers. In prestigious suburbs like Toorak and St. Ives, price cuts of $3.5 million and $3.95 million respectively have become necessary to clear inventory. These figures underscore the vulnerability of the luxury sector when capital growth slows and liquidity becomes a primary concern for owners. The prestige market often serves as a leading indicator for broader sentiment, suggesting that the era of unchallenged price growth in high-value postcodes has finally encountered a ceiling.
Beyond the metropolitan luxury hubs, the downward pressure on pricing has permeated various regional markets and more modest price brackets. In Queensland, specific areas like Middle Ridge have recorded price reductions reaching $1.25 million, while South Australia, Tasmania, and the Northern Territory have all reported substantial six-figure adjustments. This geographical breadth indicates that the correction is not merely a reaction to overvaluation in major cities but a comprehensive shift in the national property psyche. As inventory levels rise across the country, buyers are finding themselves in a position of greater leverage, allowing them to bypass properties that do not align with current market valuations. The increase in available stock provides a buffer against the frantic bidding wars seen in previous cycles, forcing vendors in even historically stable regions to reconsider their financial targets. This nationwide trend highlights the necessity for a data-driven approach to property appraisal.
Economic Realities: Drivers and Future Market Stability
Several internal and external factors are driving this massive recalibration, with over-capitalization playing a significant role in vendor disappointment. Many owners who invested heavily in bespoke renovations or high-spec builds during the previous construction boom now find that buyers are unwilling to pay a premium for specific personal tastes. Additionally, the prevalence of overly ambitious initial pricing has led to properties languishing on the market, eventually requiring steep cuts to regain buyer interest. Expert analysis from industry leaders suggests that the market is entering a cooling phase where the accumulation of inventory is outpacing current absorption rates. This buildup of stock creates a competitive environment where only the most realistically priced homes successfully move from listed to sold. Furthermore, the rise in distressed listings in certain demographics suggests that financial pressure is increasingly motivating sellers to prioritize a quick exit from their current investments.
The period of rapid correction ultimately established a more transparent and realistic framework for the Australian property sector. Sellers who recognized the shifting tides early and adjusted their strategies accordingly were able to navigate the transition with greater success than those who remained anchored to outdated valuations. This shift provided a necessary corrective to years of unsustainable growth, ensuring that the market remained accessible to a broader range of participants. Looking ahead, the focus for both buyers and sellers shifted toward thorough due diligence and a deep understanding of local micro-market dynamics rather than national headlines. Real estate professionals emphasized the importance of setting realistic expectations from the outset to avoid the stigma of a stale listing. The lessons learned during this billion-dollar recalibration served as a reminder that property remained a cyclical asset class subject to the broader forces of global supply and demand.