While a worker's personal benefit increases by eight percent annually after full retirement age, spousal benefits remain stagnant and should be claimed immediately. This reality often catches many high-net-worth individuals off guard during the finalization of a divorce settlement, as the focus
Investors must distinguish between actual coupon cash received and the specific reportable interest figure that dictates their standing with the Social Security Administration. In the current landscape of 2026, many retirees have turned to municipal bonds as a cornerstone of their fixed-income
As the calendar moves through 2026, millions of American retirees are closely monitoring the projections for the upcoming year, specifically the anticipated 3.6% Cost-of-Living Adjustment (COLA) slated for 2027. This projected increase represents one of the most substantial adjustments in recent
Wisconsin residents participating in the Affordable Care Act marketplace are facing an average premium increase of 22 percent during the current open enrollment period. This staggering figure represents a significant departure from previous years when federal interventions provided a much-needed
Relying on the default enrollment rate set by an employer often leaves workers with a balance that fails to meet their long-term financial projections. While many professionals focus on market volatility or fund performance, the most significant lever for wealth accumulation is the personal
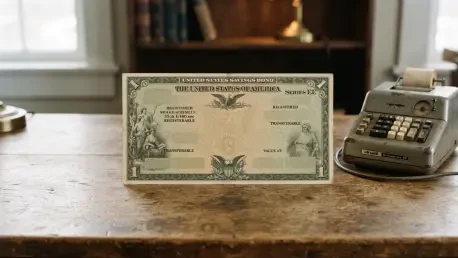
Historical comparisons show that many previously issued I bonds are currently earning only the inflation rate, putting them at a disadvantage compared to the new 1.40 percent fixed-rate issues. This specific rate represents a high for the current decade, offering a guaranteed real return that
1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34