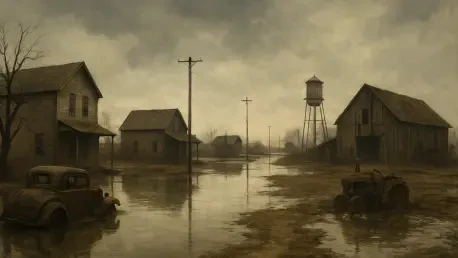
The catastrophic collapse of the American labor market reached its peak in 1933, when one-quarter of the national workforce found themselves without employment or a steady source of income. This devastating period catalyzed a total reimagining of the American social contract, shifting the nation from a state of individual vulnerability to an era of collective security. As the foundations of the global economy crumbled, the federal government transformed from a passive observer of market fluctuations into a proactive architect of social stability. This transition was driven by a combination of desperate economic necessity and the sheer resilience of a population forced to adapt to a world without traditional safety nets. The resulting structural reforms did more than just address the immediate crisis; they forged a modern regulatory framework that persists in the present day. By examining how systemic failures prompted institutional responses, it becomes clear that the crisis served as the defining crucible for the modern relationship between citizens and the state.
Resilience and Adaptation: The Survival of the American Family
During the height of the crisis, families across the nation were forced to return to a more traditional model of self-sufficiency to survive the collapse of the cash economy. This adaptation saw households becoming small-scale producers once again, with vegetable gardens appearing in urban backyards and clothing being repaired or sewn by hand to avoid unnecessary expenditures. Beyond these survival strategies, the era witnessed a radical shift in gender dynamics as women entered the workforce in unprecedented numbers to bolster dwindling household funds. Despite the social pressures of the time, these female workers became the primary financial anchors for millions of homes, preventing total ruin when male breadwinners could no longer find steady employment. This period of shared hardship fostered a deep sense of communal reliance, as neighbors pooled resources and organized informal support networks. Such grassroots resilience proved essential for maintaining the social fabric while formal institutions struggled to provide relief.
The profound financial strain of the 1930s left a permanent mark on the demographic trajectory of the United States, most notably through a sharp decline in the national birthrate. For the first time in American history, birthrates dropped below replacement levels as young couples postponed marriage and parenthood, recognizing that they lacked the resources to support a new generation. This collective hesitation reflected a deep-seated anxiety about the future, where the dream of homeownership and family stability felt increasingly unattainable for the average citizen. These personal sacrifices were not merely temporary adjustments but represented a fundamental shift in the American psyche regarding long-term planning and economic risk. Even as conditions eventually improved, the cultural memory of scarcity continued to influence how generations approached savings and domestic life. The psychological trauma of the era instilled a cautious mindset that prioritized security over speculation, a trait that would echo through decades of subsequent financial behavior.
Strengthening Financial Pillars: The Banking Act of 1933
To address the systemic fragility that led to the 1929 crash, the federal government implemented the Banking Act of 1933, which introduced the Federal Deposit Insurance Corporation. This legislative intervention was specifically designed to end the cycle of bank runs that had decimated the savings of millions of Americans by providing a government guarantee for individual deposits. By restoring public confidence in financial institutions, the government successfully transformed banks from volatile, high-risk entities into stable utilities essential for modern life. This shift was critical because it eliminated the self-fulfilling prophecy of bank failure, where fear alone could cause a healthy institution to collapse. Today, the legacy of this reform is seen in the continued trust that citizens place in the banking system, knowing that their assets are shielded from institutional insolvency. The FDIC did more than protect money; it provided the psychological foundation for a stable middle-class economy by ensuring that personal thrift was no longer a gamble.
A central pillar of the new financial architecture was the strict separation of commercial and investment banking, a measure intended to prevent the speculative excesses that triggered the Great Depression. This regulation ensured that institutions responsible for managing the daily deposits and loans of the general public were prohibited from engaging in high-stakes securities trading and Wall Street gambling. By creating a physical and legal barrier between these two functions, the government sought to insulate the people’s money from the inherent volatility of the stock market. This clear distinction provided a predictable financial environment, allowing the economy to grow without the constant threat of a market crash dragging down the savings of ordinary families. While parts of this legislation have been debated and modified in subsequent decades, the core principle remains a vital lesson in financial oversight. Maintaining a boundary between retail banking and speculative investment continues to be a primary focus for regulators seeking to balance market innovation with the need for public security.
Establishing a Safety Net: The Role of Social Security
Prior to the economic upheavals of the 1930s, the concept of a national retirement system was virtually nonexistent in the United States, leaving the elderly in a state of extreme vulnerability. Most older citizens relied on personal savings or the goodwill of family members, both of which were frequently obliterated during the prolonged downturn. The Social Security Act of 1935 was born from the realization that individual responsibility alone was insufficient to protect the population against systemic economic collapse. This landmark legislation established a national retirement plan, signaling a permanent departure from the era of purely private risk and marking the birth of the modern welfare state. By creating a government-managed framework for old-age insurance, the nation acknowledged that the state has a fundamental role in ensuring a basic standard of living for those who can no longer work. This evolution in political thought redefined the American social contract, positioning the government as the ultimate guarantor of long-term economic dignity.
The Social Security program functions as a unique intergenerational contract, where the current workforce provides the funding for the benefits received by current retirees. This structure ensures that as long as the labor market remains active, the elderly and disabled have access to a foundation of financial support that is independent of market fluctuations. Over the decades, the program has expanded its scope to include essential disability and survivor benefits, transforming it into a comprehensive safety net that protects families from the loss of a primary earner. While it was never designed to be the sole source of retirement income, its presence allows individuals to build additional private savings on a stable and predictable base. As the nation moves forward from 2026 to 2030 and beyond, the ongoing management of this system remains a central topic of public policy. The program’s ability to adapt to changing demographics highlights its role as a flexible but permanent cornerstone of American social stability and individual financial planning.
Ensuring Institutional Resilience: Future Perspectives and Solutions
The enduring legacy of the Great Depression is the entrenched belief that the federal government serves as the ultimate backstop against catastrophic economic failure. In the current landscape of 2026, Americans generally expect that their financial well-being is shielded by a complex web of regulatory safeguards and institutional protections. This transition from private liability to public security has reshaped the way citizens interact with the market, fostering an environment where long-term investment and consumption are possible. The proactive stance of the modern state in managing economic cycles is a direct result of the hard-won lessons of the 1930s, where the cost of government inaction was proven to be far too high. This institutionalized confidence is the invisible engine of the national economy, providing the stability necessary for innovation and growth. By internalizing the failures of the past, the nation has constructed a resilient framework that prioritizes the protection of household wealth as a prerequisite for broader social and political stability.
Moving forward, the primary challenge involved maintaining the integrity of these historical institutions while adapting to the technological and demographic shifts of a new era. Policy experts emphasized the necessity of implementing proactive updates to the Social Security funding model to ensure its continued viability for upcoming generations. Furthermore, strengthening the oversight of emerging digital financial platforms was identified as a critical step to prevent new forms of systemic risk from bypassing traditional banking safeguards. Legislators and financial leaders recognized that the stability established nearly a century ago required constant vigilance and reform to remain effective in a globalized economy. By focusing on transparency and the protection of individual depositors, the nation reaffirmed its commitment to the lessons learned during the 1930s. These actions ensured that the balance between market freedom and collective security remained the bedrock of American prosperity, providing a sustainable path for future economic development and individual financial peace.