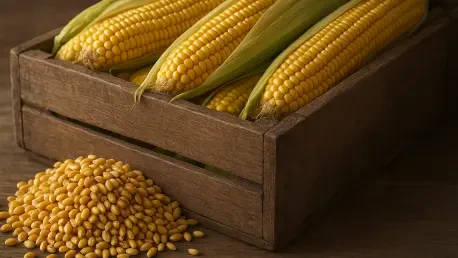
Domestic corn storage levels exceeded the average trade expectation by 171 million bushels, creating a massive supply cushion that is currently exerting downward pressure on market prices. This revelation, delivered in the latest United States Department of Agriculture Grain Stocks report, has fundamentally reshaped the 2026/27 marketing year for producers and traders across the country. The data provides a definitive count of old-crop inventories held in storage as the new harvest season commences, acting as a critical pivot point for global supply and demand projections. As the industry navigates a period of significant transition, the report highlights how massive existing reserves are meeting a challenging and uncertain new harvest environment. The unexpected surge in corn inventories, reaching a total of 2.095 billion bushels, represents a 35% increase over the previous year. This substantial surplus has caught the industry off guard, forcing a rapid recalibration of pricing strategies and logistical plans as the heavy volume of old grain competes for space with the incoming crop.
Tracking Storage Trends and Consumption Patterns
A closer look at the storage data reveals a notable shift in where these grain reserves are currently being held, with a massive 44% increase in off-farm storage at commercial elevators and warehouses. This concentration of grain in professional facilities, totaling 1.31 billion bushels, suggests that the commercial sector is carrying a much heavier burden than in previous cycles. While on-farm stocks also grew by 22% to 787 million bushels, the disparity indicates that many producers were aggressive in moving their old-crop inventory out of local bins before the 2026 harvest began in earnest. This distribution pattern is likely to have a lingering impact on the local price basis, as commercial elevators may be less inclined to offer competitive bids when their storage capacity is already pushed to the limit. For regional logistics managers, the challenge now lies in moving this existing grain to end-users efficiently enough to make room for the new corn coming off the fields during this active harvest window.
Interestingly, the report noted that grain disappearance, a key indicator of domestic and international consumption, actually rose during the summer months despite the overwhelming supply figures. Between June and August 2026, total corn usage reached approximately 3.20 billion bushels, an increase from the 3.09 billion bushels consumed during the same interval in the prior year. This uptick in consumption reflects a healthy demand from the ethanol sector and livestock feeders who have taken advantage of the available supply. However, the sheer scale of the initial carryover was so vast that even this increased demand was not aggressive enough to significantly deplete the stockpile. This mismatch between record-level consumption and even higher supply levels reinforces the existence of a massive supply cushion. Market participants must now determine if this demand trend can accelerate further or if the existing surplus will continue to weigh on the market through the rest of the 2026/27 season, potentially limiting any significant price rallies.
The Tension: Surplus Versus Harvest Realities
The timing of this surplus discovery is particularly complex because the current 2026 corn harvest is showing signs of distress across several key producing regions. With the harvest currently around 18% complete, federal crop condition ratings have revealed a notable decline in quality compared to the previous cycle. Only 57% of the remaining crop is rated in good to excellent condition, representing a sharp drop from the 66% rating observed during the same period last year. This creates a rare and tense market paradox where poor new-crop prospects would typically drive prices higher, yet the massive old-crop carryover acts as a powerful anchor. Usually, a decline in crop health triggers immediate concern among buyers, but with over two billion bushels already sitting in storage, the fear of a near-term shortage is greatly diminished. This environment places the American farmer in a difficult position where lower yields this autumn might not result in the traditional price spikes they rely on for profitability.
For the individual grower, this intersection of high supply and declining crop health necessitates a high degree of agility in both marketing and storage strategies. The presence of a historic carryover means that the seasonal price patterns the industry has come to expect may be heavily disrupted, smoothing out the volatility that usually defines the peak of the harvest. If the 2026 yields continue to trend downward as more fields are picked, the industry will rely more heavily on the existing reserves to meet international export commitments and domestic industrial needs. This reliance provides a stabilizing force for the broader economy, ensuring that food and fuel production remains consistent despite regional weather challenges. Nevertheless, the economic reality for many operations remains one of narrowed margins and logistical hurdles. Finding affordable storage space for newly harvested grain has become a primary tactical challenge, especially in areas where commercial elevators are already filled with old-crop bushels from the previous prolific production cycle.
Divergent Supply Trends: Wheat and Soybeans
In stark contrast to the abundance seen in the corn market, the wheat sector is facing an increasingly dramatic tightening of supply. National wheat production for 2026 has plummeted by 23% compared to the previous year, a decline driven by a significant 15% reduction in harvested acreage and a 10% drop in average yields. Current wheat stocks sit at 1.846 billion bushels, which is a sharp reduction from the 2.134 billion bushels recorded a year ago. Every major class of wheat, including winter, spring, and durum varieties, saw double-digit percentage declines in total production. This scarcity stands in opposition to the corn surplus and places the wheat market in a precarious position regarding its ability to meet domestic milling requirements and export orders. Flour millers and international buyers are now competing for a much smaller pool of high-quality grain, which is expected to lead to increased price volatility. This fragmentation within the grain complex highlights how different commodities can move in opposite directions even within the same marketing year.
The soybean market occupies a more balanced middle ground, reflecting a tighter supply than corn but avoiding the extreme contraction observed in wheat. Old-crop soybean stocks were reported at 315 million bushels, which is 3% lower than the previous year and slightly below the expectations of most industry analysts. This lean inventory suggests that soybean supply chains are operating with very little margin for error as the 2026 harvest gains momentum. For producers managing diversified operations, the relative scarcity of soybeans might make them a more attractive crop to move early in the season to secure necessary cash flow. The logistical priority at many shipping terminals and local elevators may shift toward soybeans due to their tighter availability and the need to fulfill immediate shipping contracts. As the 2026 harvest continues to unfold, the interplay between these three major crops will define the overall efficiency of the American transportation and storage network, as each commodity must compete for limited space and transport resources during the busiest time of the year.
Strategic Management: Adapting to New Realities
The release of the USDA data provided a clear roadmap for the challenges that defined the start of the 2026/27 marketing year. Stakeholders recognized that the massive corn surplus required an immediate shift in storage management and risk mitigation across the entire supply chain. Successful producers prioritized the liquidation of soybeans and wheat to capitalize on their tighter supply profiles while utilizing on-farm bins to hold corn in anticipation of potential market shifts later in the cycle. This strategy allowed them to manage their cash flow needs while avoiding the high costs associated with commercial storage during a period of peak occupancy. Livestock operations and ethanol plants took advantage of this environment by locking in lower input costs, effectively securing their requirements against any future volatility. By reacting quickly to the inventory figures, these organizations ensured they were well-positioned to handle the logistical bottlenecks that often arise when a large carryover meets a new harvest.
Looking forward, the industry turned its attention to the final yield results of the 2026 harvest to determine how much the new crop would offset the existing cushion. Producers were encouraged to integrate real-time field data with long-term marketing plans to navigate a landscape where traditional signals were frequently obscured by the sheer volume of grain. Integrating advanced logistics and precision demand forecasting became the most effective way to maintain profitability in a market defined by the paradox of surplus and scarcity. The agricultural sector moved toward more transparent communication between growers and commercial elevators to ensure that the massive corn pile did not disrupt the movement of other essential commodities. By adopting these proactive measures, the industry established a more resilient framework for managing the 2026/27 season, ensuring that the supply chain remained functional and responsive to global demand despite the initial shock of the inventory report.