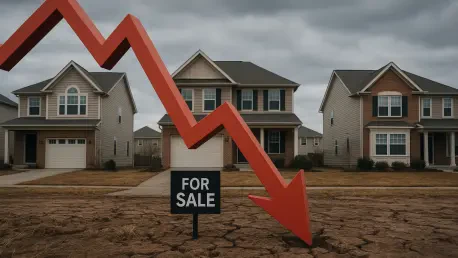
Protracted stagnation in the domestic property market remains a systemic challenge for a financial system with limited investment alternatives for average households. For nearly thirty years, the national economy relied on an aggressive model of infrastructure development and urban expansion that many analysts colloquially termed the “concrete era.” This approach allowed for rapid urbanization and provided a predictable, if increasingly fragile, mechanism for wealth accumulation among a burgeoning middle class. However, the structural foundations of this growth recently reached an undeniable breaking point, signaling the conclusion of an era where real estate served as the primary engine of prosperity. As the traditional reliance on property development falters under the weight of excessive debt and diminishing returns, a radical reimagining of the national economic strategy is currently underway. This transformation represents one of the most significant macroeconomic pivots in modern history, as the central leadership orchestrates a decisive move toward “new quality productive forces.” This strategic redirection prioritizes high-end manufacturing and sustainable energy solutions over the physical expansion of cities, attempting to redefine the nation’s global role and secure its standing as a technological superpower.
The Structural Breakdown of the Property Market
The collapse of the real estate sector has left a profound void in the national economy, considering that property and its associated industries once accounted for nearly thirty percent of the Gross Domestic Product. For decades, the residential market served as the primary vehicle for personal savings, while local governments relied heavily on land-use sales to fund their administrative budgets and infrastructure projects. This cycle was largely fueled by extreme corporate leverage, which eventually reached a level of instability that threatened the broader financial ecosystem. To mitigate these systemic risks, the government introduced the “three red lines” policy, which imposed strict limits on the borrowing capacity of major developers. The resulting liquidity crisis triggered a series of high-profile defaults, leaving a trail of unfinished housing projects and significantly diminished net worth for millions of families. This correction has effectively dismantled the long-standing “wealth effect,” leading to a noticeable decline in consumer confidence and a permanent shift in how households approach financial planning and discretionary spending.
Beyond the immediate financial fallout, the property crisis has forced a fundamental reassessment of the relationship between the state and the private sector. The era of unchecked expansion is now being replaced by a more controlled and disciplined economic environment where speculative investment is actively discouraged. This transition has proven painful for many investors who viewed apartments as a guaranteed path to financial security. With the property market no longer providing double-digit returns, the government is now tasked with managing the social implications of a cooling housing market while simultaneously seeking new drivers of growth. The shift away from real estate is not merely a policy choice but a historical necessity, as the diminishing marginal utility of additional skyscrapers and highways becomes increasingly apparent. Consequently, the focus has moved toward creating a more balanced economy that values technological innovation over the sheer volume of construction, aiming to ensure long-term stability even as short-term growth targets face significant downward pressure.
Driving the Transition to the New Three Industries
In direct response to the contraction of the property market, state resources are being funneled into an ambitious industrial vision centered on the “New Three” sectors: electric vehicles, lithium-ion batteries, and solar technology. This top-down industrial policy utilizes access to cheap credit and extensive subsidies to ensure that domestic firms can achieve global dominance through sheer scale and vertical integration. The overarching objective is to climb the global value chain, transitioning from a reputation as a low-cost manufacturer to a recognized leader in advanced technological innovation. By dominating the production of essential green technologies, the nation seeks to replace the economic activity lost during the housing slump with high-value exports that are vital to the global energy transition. This pivot is already yielding substantial results, as manufacturing clusters specialized in these new technologies emerge as the modern heart of the industrial landscape, attracting significant talent and research capital from around the world.
The results of this strategic redirection have been statistically significant, with green technology exports reaching unprecedented levels in the period from 2026 to 2028. Currently, domestic firms control more than half of the global market for electric vehicles and maintain a firm grip on the supply chains for essential battery components and photovoltaic cells. This surge in production capacity is more than a simple technological milestone; it represents a calculated effort to insulate the national economy from the volatility of the domestic housing sector. The rapid expansion of these industries has allowed for a degree of economic continuity that would have been impossible if the nation had remained tethered to the “concrete era.” However, the success of this industrial strategy also brings new challenges, particularly as the sheer volume of production begins to outpace both domestic and international demand, creating a complex environment for global trade and local manufacturers who must compete with highly efficient and state-supported production lines.
Domestic Consumption Gaps and the Export Wave
A significant challenge emerging from this new economic model is the widening gap between massive industrial output and the relatively sluggish growth of domestic consumption. While factories are churning out high-tech goods at an accelerated rate, the local population remains remarkably hesitant to increase their spending. The psychological impact of the real estate crash, coupled with a lack of comprehensive social safety nets, has encouraged households to prioritize high savings rates over the purchase of new vehicles or expensive electronics. This cautious consumer behavior creates a domestic environment where supply consistently exceeds demand, leading to deflationary pressures that further complicate the economic recovery. Without a significant boost in internal consumption, the “New Three” industries are forced to look outward, making the national economy more dependent on the global appetite for green technology than ever before. This imbalance suggests that the transition to a consumption-led economy remains a secondary priority to maintaining industrial output and employment levels.
This internal oversupply has created a massive tidal wave of affordable green technology that is now flooding international markets. For global consumers, this influx has been a boon, dramatically lowering the cost of adopting sustainable energy solutions and accelerating the transition away from fossil fuels. However, for foreign competitors, this surge represents a significant threat to their own industrial bases, as few companies can compete with the price points offered by domestic firms that benefit from massive economies of scale and state-backed financial support. The result is a complicated global marketplace where the benefits of cheaper green tech are balanced against the risks of market monopolization. This dynamic is forcing international trade partners to consider aggressive measures to protect their own emerging industries, as they fear the potential hollowing out of their domestic manufacturing sectors in the face of such a dominant export force. The tension between providing affordable climate solutions and maintaining fair industrial competition is becoming a central theme in global economic discourse.
International Trade Barriers and Global Friction
The rapid influx of green exports has triggered a defensive response from Western trading partners who are wary of repeating the industrial disruptions seen in previous decades. In an effort to protect their own nascent green industries, jurisdictions such as the United States and the European Union have implemented a series of aggressive trade barriers and tariffs. These measures specifically target electric vehicles, semiconductors, and solar panels, aiming to counter what international regulators perceive as predatory overcapacity supported by non-market mechanisms. This protectionist shift marks a significant departure from the era of hyper-globalization, as nations prioritize economic sovereignty and the preservation of domestic manufacturing jobs over the immediate benefits of cheaper imports. The resulting trade friction is creating a fragmented global market where the flow of technology is increasingly governed by political considerations rather than purely economic ones, leading to higher costs for some consumers and more complex logistics for producers.
To navigate these mounting restrictions, many domestic firms are demonstrating remarkable agility by restructuring their global supply chains and expanding their physical presence abroad. By establishing manufacturing facilities in regions like Southeast Asia, Eastern Europe, or Latin America, these companies seek to bypass direct tariffs and maintain access to critical Western markets. This tactical shift not only allows them to comply with local content requirements but also makes the global trade landscape increasingly opaque, as products are often partially assembled in third-party nations to obscure their origin. This strategy of “offshoring” domestic capacity helps to sustain production levels even as direct export routes are closed off. However, this trend also complicates the efforts of international regulators to monitor the flow of subsidized technology and ensures that trade tensions will likely remain a persistent feature of the global economy for the foreseeable future. The cat-and-mouse game between protectionist policies and corporate restructuring is redefining the boundaries of international trade and industrial policy.
The Geopolitical Battle for Green Supremacy
The competition for dominance in green technology is fundamentally a geopolitical struggle as much as it is an economic one. Currently, a significant strategic advantage is held through the control of the upstream processing of critical minerals and the majority of the global battery supply chain. While Western nations are actively working to build independent and resilient supply chains, they are often hindered by higher labor costs, more stringent environmental regulations, and a relative lack of existing technical infrastructure. This dominance in the materials that power the modern world provides a level of leverage that was previously seen only in the oil and gas markets of the 20th century. As the world moves toward a decarbonized future, the control over lithium, cobalt, and rare earth elements has become a central pillar of national security and economic strategy. This concentration of power in a single region has led to a global race to secure alternative sources of these materials, further intensifying the rivalry between major economic blocs.
This rivalry creates a difficult dilemma for global climate policy, as the world struggles to balance the urgent need for a green transition with the desire for industrial competitiveness. While cheap and high-quality components from the East are essential for meeting carbon reduction targets quickly, a total reliance on these imports may undermine the domestic industrial bases and energy security of other nations. Consequently, world leaders are now forced to make difficult choices between the pace of climate action and the health of their own manufacturing sectors. The geopolitical landscape is increasingly characterized by a “green arms race,” where success is measured not just by carbon neutrality, but by the ability to control the technologies and resources that make that neutrality possible. This dynamic ensures that the global green transition will be a volatile and highly contested process, with economic and political influence shifting toward those who can best navigate the complexities of modern industrial manufacturing and resource management.
Labor Market Shifts and Financial Reform
The domestic transition from a property-heavy economy to a high-tech manufacturing powerhouse is creating significant friction within the local labor market. The construction sector, which once provided steady employment for millions of low-skilled and migrant workers, is no longer the reliable source of income it once was. As projects stall and the demand for new building slows, these workers face a difficult and often uncertain path to re-employment. In contrast, the high-tech manufacturing sector requires a more specialized and highly educated workforce, creating a widening skill gap that leaves a substantial portion of the population behind. This demographic shift is placing downward pressure on wages for those unable to transition to the “new economy,” potentially exacerbating income inequality and creating social tensions that the government must carefully manage. The challenge of re-skilling a massive workforce is a multi-generational task that requires significant investment in vocational training and education reform.
Furthermore, the lack of a robust and transparent stock market prevents the middle class from finding viable alternatives to real estate for wealth preservation and long-term investment. Without significant financial reform to create reliable investment vehicles, much of the nation’s private capital remains trapped in low-yield savings accounts or struggling insurance products. This capital stagnation further suppresses domestic demand, as households do not feel the sense of financial security necessary to increase their spending. To truly move away from the property-led model, the financial system must evolve to provide diverse and trustworthy options for individual investors. Until such reforms are implemented, the economy will likely remain overly reliant on an export-heavy growth model to sustain national development. The success of the current economic pivot therefore depends not only on the production of batteries and electric vehicles but also on the ability to modernize the internal financial architecture to support a more resilient and consumption-oriented society.
Future Outlook for the Global Economic Order
The stability of the global economic order depended on whether domestic policy shifts successfully stimulated internal demand while simultaneously reforming the structural foundations of the financial system. For the period leading into 2026, the international community observed as the massive imbalance between industrial production and anemic domestic consumption forced a relentless surge of high-tech exports onto the global market. This period was characterized by a sharp divide between those who benefited from affordable green technology and those who viewed the influx as a threat to their industrial sovereignty. Policymakers in Western capitals responded with increasingly sophisticated trade barriers, yet the agility of manufacturers to reroute supply chains through third-party nations kept the flow of subsidized technology largely intact. The trajectory of the global green transition was ultimately dictated by this aggressive economic evolution, which prioritized manufacturing dominance as a replacement for the lost momentum of the domestic property sector.
Moving forward, the global community must recognize that the era of “pouring concrete” has been permanently replaced by a more strategic and technologically driven industrial competition. To maintain a functional global trade system, international organizations and national governments should focus on creating transparent standards for industrial subsidies and carbon border adjustments that account for the environmental and social costs of production. Investors and business leaders would be well-advised to prepare for a more fragmented market where local manufacturing presence and supply chain resilience are as important as cost efficiency. The focus should shift toward collaborative frameworks that allow for the sharing of green technology while protecting the economic interests of diverse industrial bases. By prioritizing the development of localized supply chains and investing in domestic re-skilling programs, nations can better navigate the challenges posed by the shift in global manufacturing power and ensure a more balanced and sustainable economic future for all participants.