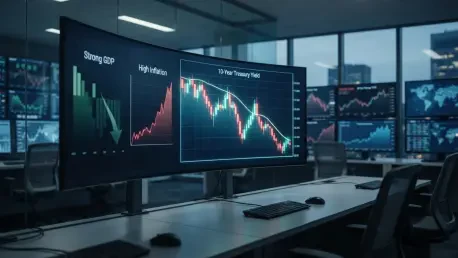
Although annual PCE inflation reached 3.6%, the figure was slightly lower than the 3.7% forecast, providing a brief window of relief for bond investors. This unexpected nuance in the data prompted a rally in the bond market even as the broader economic landscape signaled robust growth and persistent pricing pressures. In late October 2026, the benchmark 10-year Treasury yield retreated by more than 8 basis points to settle at 4.964%, managing to stay just under the critical 5% psychological threshold that has recently captivated market participants. Simultaneously, the 2-year yield, which serves as a barometer for short-term central bank policy expectations, saw a more pronounced decline of 10 basis points, landing at 4.629%, while the 30-year yield dipped to 5.31%. Stephen Coltman of 21shares noted that this inverse relationship between bond prices and yields indicates that fixed-income buyers are potentially looking past current volatility, betting that the Federal Reserve might adopt a less aggressive posture than feared.
Central Bank Policy: Navigating a Restrictive Financial Environment
The resilience of the domestic economy continues to defy expectations, with third-quarter Gross Domestic Product showing an annualized growth rate of 3.4%. This performance notably exceeded the 3.1% expansion predicted by several leading economists, illustrating a durable consumer base and steady industrial activity. However, this growth has not arrived without a cost, as the Personal Consumption Expenditures price index remains a point of significant concern for the Federal Reserve. The monthly increase of 0.5% in the PCE index suggests that underlying price pressures are not fading as quickly as many had hoped. While the annual rate of 3.6% was a marginal improvement over some projections, it represents a notable acceleration from levels recorded in August. Analysts like Ali Hassan of Thornburg Investment Management suggest that this divergence creates a complex environment for investors. Currently, market tools indicate a 77% probability of a quarter-point increase in December.
Navigating the final months of the year required a strategic emphasis on defensive positioning and liquidity management. Investors who anticipated a more restrictive environment successfully shielded their portfolios by shifting toward shorter-duration assets as the Fed’s communication became increasingly hawkish. The conclusion of the October policy cycle demonstrated that while growth remained strong, the path toward price stability was longer than initially anticipated. Looking ahead, institutional players should prioritize monitoring real-time inflation swaps and labor participation rates to gauge the likelihood of a December rate hike. If policymakers provide clear signals of further tightening, the recent decline in yields will likely reverse, pushing the 10-year rate back toward the 5% mark. Professionals must remain agile, utilizing dynamic hedging strategies to mitigate the impact of sudden shifts in central bank sentiment. Future stability will depend on the market’s ability to absorb these adjustments.