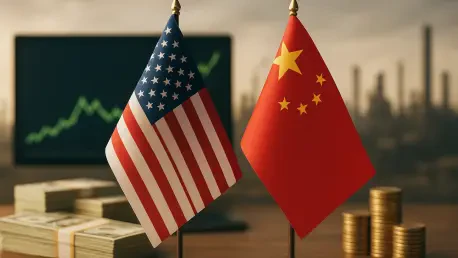
The absence of soybeans from the list of approved agricultural concessions suggests that China is maintaining a strategic posture regarding its critical food supply dependencies. This specific omission served as a sobering reminder during the recent high-stakes summit in Washington, where President Donald Trump and Chinese President Xi Jinping finalized a deal to reduce tariffs on approximately $60 billion in bilateral trade. As the world navigates the complexities of the current fiscal year, this agreement represents a significant cooling of economic tensions that had previously reached a breaking point. Only a short time ago, duties on a vast array of goods had spiked to an unprecedented 145 percent, threatening to sever the commercial ties between the two largest economies on the planet. By focusing strictly on nonsensitive products that do not compromise national security or high-tech industrial advantages, both administrations are attempting to find a middle ground that provides immediate relief to their domestic markets while maintaining their long-term competitive edges.
Mechanics of the Tariff Adjustments
Returning to Global Trade Standards: The MFN Transition
The technical foundation of this agreement centers on the restoration of Most-Favored-Nation status for specific categories of goods, effectively dismantling the punitive surcharges that defined the previous trade cycle. Under established international guidelines, this transition allows selected products to bypass country-specific penalties and return to standard, single-digit tariff rates. This mechanical shift is expected to provide a substantial boost to liquidity for importers who have struggled under the weight of triple-digit duties since 2024. For the Chinese commerce ministry, this involves granting a reprieve to 1,619 categories of American exports, ranging from processed timber to advanced medical equipment. By aligning these specific goods with broader global trade standards, the agreement creates a predictable framework for businesses that have spent years navigating erratic policy shifts. This return to a standard tariff baseline is less a total reconciliation and more a pragmatic reset of the operational costs for essential commodities.
Strategic Allocation: Categorizing Nonsensitive Product Lists
The American approach to this de-escalation has been meticulously curated to target consumer-facing sectors where lower costs offer the most direct political and economic dividends. The list of 77 categories approved by the U.S. Trade Representative focuses heavily on seasonal goods, toys, and household tableware—items that constitute a significant portion of the average family’s annual spending. By lowering the barriers for these specific Chinese exports, the administration is providing a necessary buffer against the rising cost of living without exposing critical domestic industries to state-subsidized competition. This selective liberalization demonstrates a sophisticated understanding of supply chain vulnerabilities, ensuring that while the battle for technological supremacy continues, the trade of daily necessities remains relatively unencumbered. The calculated nature of these lists reflects a broader strategy of isolating economic relief from the more contentious issues of national defense and strategic industrial sovereignty, allowing for a stabilized flow of consumer goods across the Pacific.
Economic Implications for Consumers and Markets
Assessing Deflationary Pressures: Impact on Households
The immediate macroeconomic objective of this bilateral reduction is the containment of inflationary pressures that have hampered domestic growth throughout the early months of this year. Economists at major financial institutions like Natixis and ING Bank suggest that the influx of lower-priced Chinese consumer goods will act as a significant deflationary force, effectively easing the financial burden on American households during a period of high interest rates. For China, the deal provides a vital outlet for its industrial overcapacity in low-tech manufacturing sectors, allowing its factories to maintain employment levels by servicing the massive U.S. retail market. While the overall average U.S. tariff on Chinese goods is only projected to drop from 22 percent to approximately 20.5 percent, the targeted nature of the cuts means that the impact on specific consumer price indices could be much more pronounced. This targeted relief provides a safety valve for the economy, allowing for a period of managed stability while both nations continue to recalibrate their broader trade policies.
Selective Market Access: Reaching Emerging Chinese Segments
For American brand owners and agricultural exporters, the deal provides improved access to several fast-growing niches within the Chinese domestic market. By moving products like premium hair care and infant formula toward more favorable duty structures, the agreement allows American firms to compete more effectively for the burgeoning Chinese middle class. However, the decision to exclude major commodities like coal and certain grains from the most significant cuts indicates that trade remains a tool of geopolitical leverage. While the opening for consumer brands is a positive development, it is being treated by industry analysts as an incremental victory rather than a wholesale market reopening. The selective nature of this access forces American companies to remain agile, focusing on brand loyalty and product quality in sectors where the Chinese government feels less threatened by foreign dominance. This environment of restricted but functional trade requires a nuanced approach to market entry, emphasizing the long-term potential of consumer loyalty over the rapid expansion of high-volume commodity shipments.
Strategic Boundaries and Future Challenges
The Technology Fortress: Protecting Critical National Sectors
A defining characteristic of this trade agreement is the absolute lack of movement regarding strategic technological sectors, which remain shielded by high tariffs and export controls. Neither Washington nor Beijing showed any willingness to negotiate on semiconductors, electric vehicles, or advanced battery technology during the summit proceedings. These industries are viewed as the bedrock of future national security and economic sovereignty, and both nations are committed to maintaining a high degree of protectionism to foster domestic innovation. This “technology fortress” approach ensures that while toys and timber flow more freely, the structural competition for the digital and green energy future remains as intense as ever. The bifurcation of trade into sensitive and nonsensitive categories is now a permanent feature of the bilateral relationship, signaling that the era of unfettered globalization has been replaced by a more fragmented and cautious model of engagement. Businesses operating in these high-stakes fields must continue to expect significant regulatory hurdles and geopolitical scrutiny for the foreseeable future.
Institutional Oversight: Addressing Industrial Capacity Issues
The long-term stability of this agreement is further complicated by the ongoing Section 301 investigations into Chinese industrial capacity and state subsidies. The U.S. administration continues to monitor 15 key partners to determine if excess manufacturing capacity is being used to distort global prices and harm domestic producers. Depending on the findings of these probes, which are expected to conclude late this year, new duties could be triggered on products not covered by the current deal, potentially negating the broader economic gains. Furthermore, the diplomatic calendar through November 2026 and December 2026, which includes major summits in Shenzhen and Florida, suggests that both sides are seeking a temporary period of calm to assess the results of these current reductions. This window of predictability provides a necessary breathing room for global supply chains, but the threat of future institutional action remains a significant variable. The current trade truce is a fragile bridge toward a more sustainable equilibrium, requiring constant oversight and diplomatic maintenance to prevent a sudden return to escalation.
Managed Deescalation and Market Stabilization
The reciprocal tariff reductions finalized this month provided a blueprint for how the world’s two largest economies might navigate a path toward managed de-escalation in a post-globalization era. By isolating consumer goods from the broader technological and military competition, the agreement successfully lowered the immediate cost of living for millions while preserving the strategic leverage necessary for future negotiations. Market participants observed that the $60 billion package functioned more as a symbolic gesture of stability than a total overhaul of the trade regime, yet its psychological impact on the financial sector was profound. Corporations were advised to utilize this period of relative calm to diversify their supply chains further and invest in localized manufacturing, rather than relying on a permanent return to the trade conditions seen before the current protectionist cycle. The move to Most-Favored-Nation status for daily necessities demonstrated that even in a state of intense competition, pragmatic cooperation remained possible when domestic economic stability was at stake. Leaders acknowledged that the path forward required a delicate balance between national security and the unavoidable realities of economic interdependence through the end of the year and into the next decade.