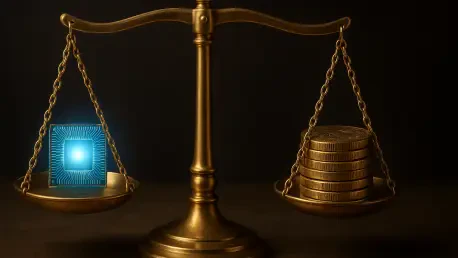
Real estate accounted for sixteen percent of the U.S. GDP in 2008, a factor that ensured a housing crash would suppress consumer spending in a way that a semiconductor dip cannot. Today, in 2026, the technology sector remains the primary engine of global market growth, yet the rapid ascent of artificial intelligence has introduced a layer of volatility that feels uncomfortably familiar to seasoned observers. While major indices hover near historic peaks, a localized storm is brewing within the specific hardware and software companies that have underpinned the rally over the last several years. The core of the debate is no longer about the utility of machine learning, but rather whether the financial infrastructure supporting it is structurally sound or destined for a painful recalibration. This tension between innovation and speculation creates a unique environment where the line between a healthy market correction and a systemic collapse becomes increasingly blurred as investors navigate through uncertain valuations.
Analyzing Historical Parallels: The Risk of Systemic Failure
The chilling parallels to the 1999–2000 Dotcom era are difficult to ignore when examining the trajectory of recent semiconductor valuations. During that period, the Nasdaq plummeted by a staggering seventy-five percent, and even the most innovative companies required fifteen years to recover their previous market highs. The lesson from the turn of the century was that even when a technology like the internet is truly transformative, the financial enthusiasm surrounding it can become so detached from reality that it leads to widespread ruin. In 2026, semiconductor companies represent a record-breaking percentage of the S&P 500, a concentration that surpasses the peak of the 2000 bubble. Critics argue that this level of “irrational exuberance” has pushed the market to a breaking point where the slightest missed target could trigger a cascading sell-off. As AI chip manufacturers see their market caps swell to trillions, the pressure to maintain exponential growth rates creates a precarious high-wire act for the entire market.
Beyond the simple comparison to stock prices, some analysts see deeper structural parallels to the 2008 Global Financial Crisis through the emergence of “circular financing” models. This phenomenon occurs when tech giants and venture capital firms fund the very startups that buy their hardware, creating a closed-loop ecosystem that artificially inflates revenue figures. If the startups cannot monetize their AI services effectively, they stop buying hardware, which in turn hurts the balance sheets of the giants that funded them. This interconnected web of debt and investment mirrors the complexity of the sub-prime mortgage securities that triggered a global meltdown over a decade ago. If the infrastructure supporting the current boom is built on such excessive leverage, the failure of a single major player could potentially drag the broader economy into a recession. The current private credit market, now worth trillions, adds another layer of complexity, as rising insurance costs against corporate defaults suggest that the financial landscape is becoming a tinder box.
Evaluating Market Fundamentals: Economic Resilience and Future Outlook
Despite the mounting alarm, a closer inspection of current market fundamentals reveals a significant divergence from the speculative frenzy of the late nineties. During the 2000 bubble, the Nasdaq forward price-to-earnings ratio reached an astronomical level of seventy; today, that figure remains far more anchored near thirty. This suggests that while valuations are high, they are not completely untethered from actual corporate earnings. Furthermore, unlike the unprofitable “dotcoms” that were often little more than ideas on a whitepaper, the firms dominating the current AI landscape are established global leaders. These corporations possess massive cash reserves, proven business models, and significant operating margins that allow them to weather periods of slowing growth. This profitability acts as a critical safety net that was conspicuously absent twenty-five years ago. The capital expenditure being poured into AI is coming from companies with billions in existing annual net income, rather than from speculative venture debt alone.
Moreover, the structural impact of a potential correction in the technology sector today would likely be far less catastrophic than the 2008 housing collapse. Because real estate is the primary asset for the majority of American households, a crash in that sector directly erodes consumer confidence and suppresses spending across all demographics. In contrast, a dip in semiconductor stocks or high-growth software equities has a much more localized effect, primarily impacting high-net-worth individuals and institutional portfolios rather than the essential solvency of the average family. Since the 2008 crisis, the financial system has also undergone significant fortification through stricter banking regulations and increased capital requirements. These safeguards were specifically designed to prevent the total credit market freezes that characterized the Great Recession. This regulatory environment provides a substantial buffer, making a decade-long economic contraction highly unlikely even if the current enthusiasm for artificial intelligence undergoes a sharp and necessary correction.
The path forward required a strategic pivot toward sustainable monetization and rigorous risk management rather than a reliance on speculative momentum. History showed that while market corrections were painful in the short term, they served a vital function in clearing out inefficient capital and refocusing investment on truly productive enterprises. Stakeholders who prioritized transparency in AI revenue streams and diversified their portfolios across non-tech sectors were better positioned to navigate the shifts that emerged during this period. The evolution of the financial landscape suggested that the most effective strategy involved balancing the undeniable potential of machine learning with a sober assessment of operational costs. Moving beyond the initial hype, organizations found that focusing on specific, high-ROI applications was more beneficial than general infrastructure spending. This shift in perspective allowed the industry to mature as firms prioritized actual utility over speculative expansion, ensuring that the technology remained a cornerstone of future economic development.