The acquisition of Restaurant Depot provides Sysco with immediate access to a cash-and-carry market segment valued between $60 billion and $70 billion. This monumental transaction serves as the centerpiece of a larger strategic pivot across the entire foodservice distribution landscape, where the historical focus on simple volume-based growth has been replaced by a more sophisticated philosophy known as “Beyond Scale.” For decades, the primary goal of mergers and acquisitions was horizontal consolidation—essentially the big getting bigger to maximize purchasing power. However, the modern landscape increasingly favors a strategy where the broad gets broader, enabling market leaders to capture a greater share of the operator’s total spend. By utilizing targeted acquisitions, these massive organizations are successfully accessing previously untapped market segments and securing specialized capabilities that would be far too time-consuming or expensive to develop through organic means alone.
The Landmark Shift: Multi-Channel Fulfillment Strategies
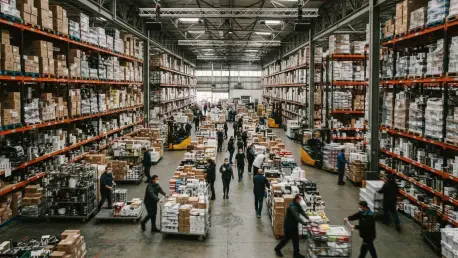
This defining era of consolidation is characterized by Sysco’s massive $29 billion agreement to integrate Restaurant Depot, a move that signals a fundamental change in how broadliners perceive fulfillment logistics. By absorbing over 160 large-format cash-and-carry locations, Sysco is not merely padding its bottom line with an additional $16 billion in projected revenue; it is actively diversifying its service model to engage more than 700,000 independent restaurant operators. These customers often value the immediate gratification and lower price points of a self-service model over the traditional scheduled delivery systems that have long defined the industry. The integration allows a massive distributor to bridge the gap between high-volume logistics and the needs of smaller, more agile food businesses that operate on tight margins and unpredictable timelines. This strategic expansion into adjacent channels ensures that the industry giants remain essential partners to every tier of the foodservice world.
Building on this trend of channel diversification, other major players like Performance Food Group have looked toward the convenience sector to insulate their business models against market volatility. The acquisition of Core-Mark significantly bolstered their presence in the convenience store channel, moving their revenue in that specific segment from $5 billion to more than $20 billion in a relatively short period. Similarly, US Foods has explored retail-adjacent platforms like CHEF’STORE to capture a more diverse customer base, although the challenges of realizing internal synergies remain a constant point of discussion among industry analysts. This collective shift suggests a realization that long-term enterprise value now depends on a presence across multiple sales channels rather than a reliance on traditional bulk distribution alone. As the boundary between wholesale and retail-style self-service continues to blur, distributors are forced to rethink their infrastructure to accommodate a much wider variety of fulfillment speeds.
Targeted Diversification: Acquiring Niche Expertise and Specialty Services
To transition into the role of a “one-stop shop,” leading distributors are increasingly hunting for niche experts that can bolster their specialty product portfolios and high-margin service offerings. Sysco’s recent acquisitions of companies like Edward Don, which focuses on equipment and supplies, and Greco & Sons, an Italian specialty provider, highlight an effort to move beyond commodity food items. These moves allow a distributor to act as a comprehensive consultant for restaurant operators, offering everything from commercial kitchen design to artisanal imported ingredients. By providing specialized services that require deep product knowledge, distributors can move away from low-margin competitive bidding and toward a value-added partnership. This shift is critical as operators seek streamlined supply chains where a single partner can fulfill diverse needs ranging from heavy kitchen machinery to the most delicate specialty produce or artisanal proteins.
While the largest organizations continue to consolidate, independent and regional distributors have found ways to maintain a vital and resilient role in the market by doubling down on their unique local advantages. These mid-sized players often succeed by leveraging high-touch customer relationships and specialized sourcing capabilities that massive, standardized corporations find difficult to replicate. Interestingly, major mergers among the “behemoths” often create brief windows of opportunity for these agile local operators. When large-scale integrations lead to service lapses, logistical friction, or employee turnover, independent distributors are frequently prepared to step in and capture displaced market share. By focusing on route density and deep-rooted expertise in specific geographic areas, these smaller firms prove that personalized service and local product knowledge remain powerful differentiators in an industry that is otherwise trending toward massive, centralized corporate structures.
Strategic Imperatives: Navigating Regulatory and Demographic Pressures
The current trajectory of M&A is also being heavily influenced by an increasingly rigorous regulatory environment and shifting demographic realities within business ownership. With the Federal Trade Commission maintaining a close watch on “pure-play” consolidation that could potentially stifle local competition, major distributors are incentivized to pursue acquisitions in adjacent markets. This strategy allows firms to grow their capabilities without necessarily triggering the antitrust concerns that arise when two direct competitors in the same geography attempt to merge. Furthermore, a significant wave of succession-driven sales has emerged as the owners of long-standing family businesses reach retirement age and seek exit strategies. This demographic shift provides a steady pipeline of opportunities for larger firms to acquire established local routes and specialized knowledge bases that have been built over decades, ensuring a continuous infusion of local talent into larger corporate frameworks.
As the industry moved forward, successful organizations realized that the path to sustained growth required a sophisticated blend of logistical scale and specialized nuance. The winners in this competitive landscape were those who recognized that acquiring a company was merely the first step; the true challenge resided in maintaining the service culture of the acquired entity while leveraging the back-end efficiency of a global supply chain. Strategic leaders prioritized vertical integration and invested heavily in alternative fulfillment models to stay ahead of changing operator preferences. They discovered that by focusing on high-margin categories like specialty proteins and kitchen technology, they could insulate their businesses from the commodity price fluctuations that often plagued traditional distributors. Ultimately, the industry transitioned into a period where the ability to offer a diverse, multi-channel experience became the primary benchmark for success, proving that enterprise diversity was the most effective safeguard against market disruption.