A high multiple paired with significant deferred risk may actually result in less walkaway money for a seller than a lower multiple paid entirely in cash. Navigating the financial landscape of manufacturing in early 2026 requires a clear understanding of how valuations are actually calculated versus how they are reported in the media. Many business owners fall into the “headline trap,” assuming that the high multiples cited in recent financial news apply to their specific operations without adjustment. In reality, manufacturing valuations are a complex blend of industry averages and granular financial metrics that vary across different sectors and company sizes. While broad market reports might suggest that multiples have climbed to an average of 7.3x, the underlying data reveals a massive range spanning from below 2x to over 27x for specialized firms. Understanding this distinction between broad market trends and the specific economic drivers of a single plant is the first essential step toward achieving an accurate appraisal of worth.
Defining the Core Valuation Metrics: SDE and EBITDA
The choice between using Seller’s Discretionary Earnings (SDE) and Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) is perhaps the most significant factor in determining a manufacturing firm’s value. SDE is typically reserved for smaller, owner-operated shops where the owner’s salary and personal benefits are added back into the profit to show the total financial benefit to a single operator. This metric accounts for the fact that in a small shop, the owner often wears multiple hats, acting as the lead engineer, sales manager, and human resources director simultaneously. When a buyer evaluates an SDE-based business, they are essentially looking at what one person can expect to earn by owning and operating that specific job. Because this model relies heavily on the individual at the top, the multiples applied are generally lower, reflecting the increased operational risk that occurs if the owner were to suddenly exit the business or become incapacitated.
In contrast, EBITDA is used for larger manufacturing enterprises and assumes that the cost of a professional management team is already accounted for in the operating expenses. This metric is favored by institutional investors because it provides a clearer picture of the company’s ability to generate cash flow regardless of who is in the corner office. Applying a high EBITDA multiple to an SDE-based business can lead to dangerously inflated expectations, often doubling the perceived value of the company beyond what the market is willing to pay. For instance, if an owner is currently taking a high salary and reporting low EBITDA, a simple multiple of that EBITDA will drastically undervalue the business unless the owner’s compensation is properly adjusted back to market rates. Sellers must ensure that their financial statements are recast to show a pro forma environment that reflects a professional management structure, thereby providing a more accurate foundation for valuation.
The Size Premium: Why Scale Mitigates Risk
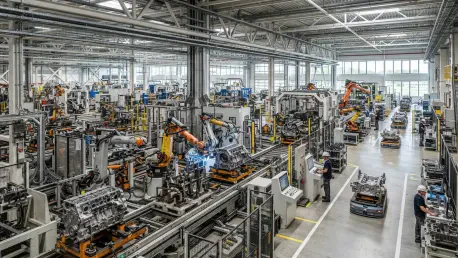
In the manufacturing sector, company size is a primary driver of valuation multiples because scale typically correlates with reduced operational risk. Larger firms command a size premium because they offer institutional stability that smaller shops simply cannot match. For example, a mid-sized fabrication plant with $50 million in annual revenue usually possesses a diversified customer base, meaning no single client accounts for more than ten percent of total sales. This diversification protects the business from the sudden loss of a major contract, which would be catastrophic for a smaller shop with only two or three primary customers. Recent market data from early 2026 indicates that a small machine shop might see a multiple below 4x, whereas a large-scale manufacturer can command multiples exceeding 12x. This discrepancy is not an indictment of small businesses but a reflection of the capital required to mitigate the inherent volatility found in smaller manufacturing operations.
Beyond just revenue figures, institutional stability is defined by the depth of a company’s management layer and the quality of its internal systems. Acquirers are willing to pay more for a business that can function independently of its owner, as this suggests the company has robust standard operating procedures and a capable leadership team. Clean financials and professionalized accounting practices also play a major role in securing a higher multiple, as they reduce the time and risk associated with the due diligence process. Companies that have invested in modern Enterprise Resource Planning (ERP) systems and ISO certifications often find themselves at the higher end of the valuation spectrum. These certifications and technological investments serve as a proxy for quality and reliability, signaling to a potential buyer that the business is a turnkey operation. Consequently, the size premium is actually a risk discount given to companies that have successfully professionalized their infrastructure.
Tactical Approaches for Maximizing Manufacturing Worth
A high valuation on a Letter of Intent does not always translate to a large check at the closing table, as deal structure remains the ultimate arbiter of value. Data across thousands of recent manufacturing transactions reveals that all-cash deals are relatively rare, with the majority of sellers receiving only about seventy-eight percent of the purchase price upfront. The remainder of the deal is frequently tied up in seller notes, where the seller essentially acts as the bank for the buyer, or earnouts, which are contingent on the company meeting specific performance targets in the future. These deferred payments carry the risk of never being fully realized if the business faces a downturn or if the new management fails to execute the growth strategy. Because of this, a lower all-cash offer is often more financially sound than a higher headline price that is heavy on contingencies. Sellers must carefully weigh the time-value of money against the potential upside of an earnout before signing.
The analysis of thousands of recent manufacturing transactions suggested that successful sellers prioritized market alignment over headline hunting. It was observed that owners who professionalized their EBITDA by adjusting compensation to market rates and decoupling their daily involvement from operations secured significantly higher offers. Those who engaged with niche databases like Bizcomps or DealStats rather than general news reports achieved valuations that stood up to the scrutiny of due diligence. By treating every dollar of a deferred payment as a risk-adjusted promise rather than a guarantee, sellers negotiated from a position of factual strength. These owners focused on building institutional independence, which ultimately allowed them to exit their businesses with the maximum possible cash at close. Moving forward, the most effective strategy involved preparing for a sale at least twenty-four months in advance to ensure all financial metrics were optimized for the specific buyer pools active in the 2026 market.